Vietnam’s Central Bank Takes Tough Action: Banks Must Lower Lending Rates
Vietnam’s economy has been growing rapidly this year, but businesses are still complaining about borrowing. On October 19, the central bank summoned senior executives from 46 banks and demanded that they lower lending rates. The day before, it had already required synchronized cuts in deposit and lending rates; if implementation is weak, banks’ credit quotas may also be lowered.
Central Bank’s Stance: The Logic of Rate Cuts Is No Longer Ambiguous
The central bank requires that posted deposit rates for terms of six months and above be cut by at least 0.5%, and that lending rates for production and business activities and priority sectors be reduced by 1.5 to 2 percentage points. Banks that do not cooperate may have their credit quotas lowered. High-risk loans such as real estate and large loans must also comply.
Credit quotas affect how much banks can lend, so this demand carries clear pressure. The central bank wants banks to make profit concessions, while also requiring that they not lend indiscriminately.

Vietnam’s central bank summoned senior executives from 46 banks, demanding lower financing costs and stronger enforcement. Source: https://kevesko.vn/
Fast Economic Growth Means Businesses Need More Funds
Vietnam’s GDP grew 9.95% year on year in the third quarter and 9.01% in the first nine months. To sustain growth, factories need to add equipment and stock raw materials, and the government also needs to advance transportation and urban construction, so demand for funds is increasing accordingly.
Bank lending is growing faster than deposit mobilization, so banks have had to raise deposit rates to retain funds. Some banks’ annual deposit rates are close to 10%; with higher costs, it is difficult for corporate borrowing rates to fall substantially.

Manufacturing and infrastructure require sustained investment, and borrowing costs directly affect companies’ expansion plans. Source: https://nhadautu.vn/
Why Bank Rate Cuts Are Difficult: Deposit Costs
Some banks have already introduced preferential offers. BIDV’s short-term Vietnamese dong lending rate starts at 6% per year; Vietcombank has promised to cut rates by at least 2% before the end of the year; Agribank offers qualified customers rate cuts of up to 2%. But the preferential terms apply only to designated industries and customers meeting credit conditions.
Although banks are lowering lending rates, loan quality cannot be compromised. If lending grows too fast after rate cuts and borrowers cannot repay, bad debts will increase, making banks more conservative instead.
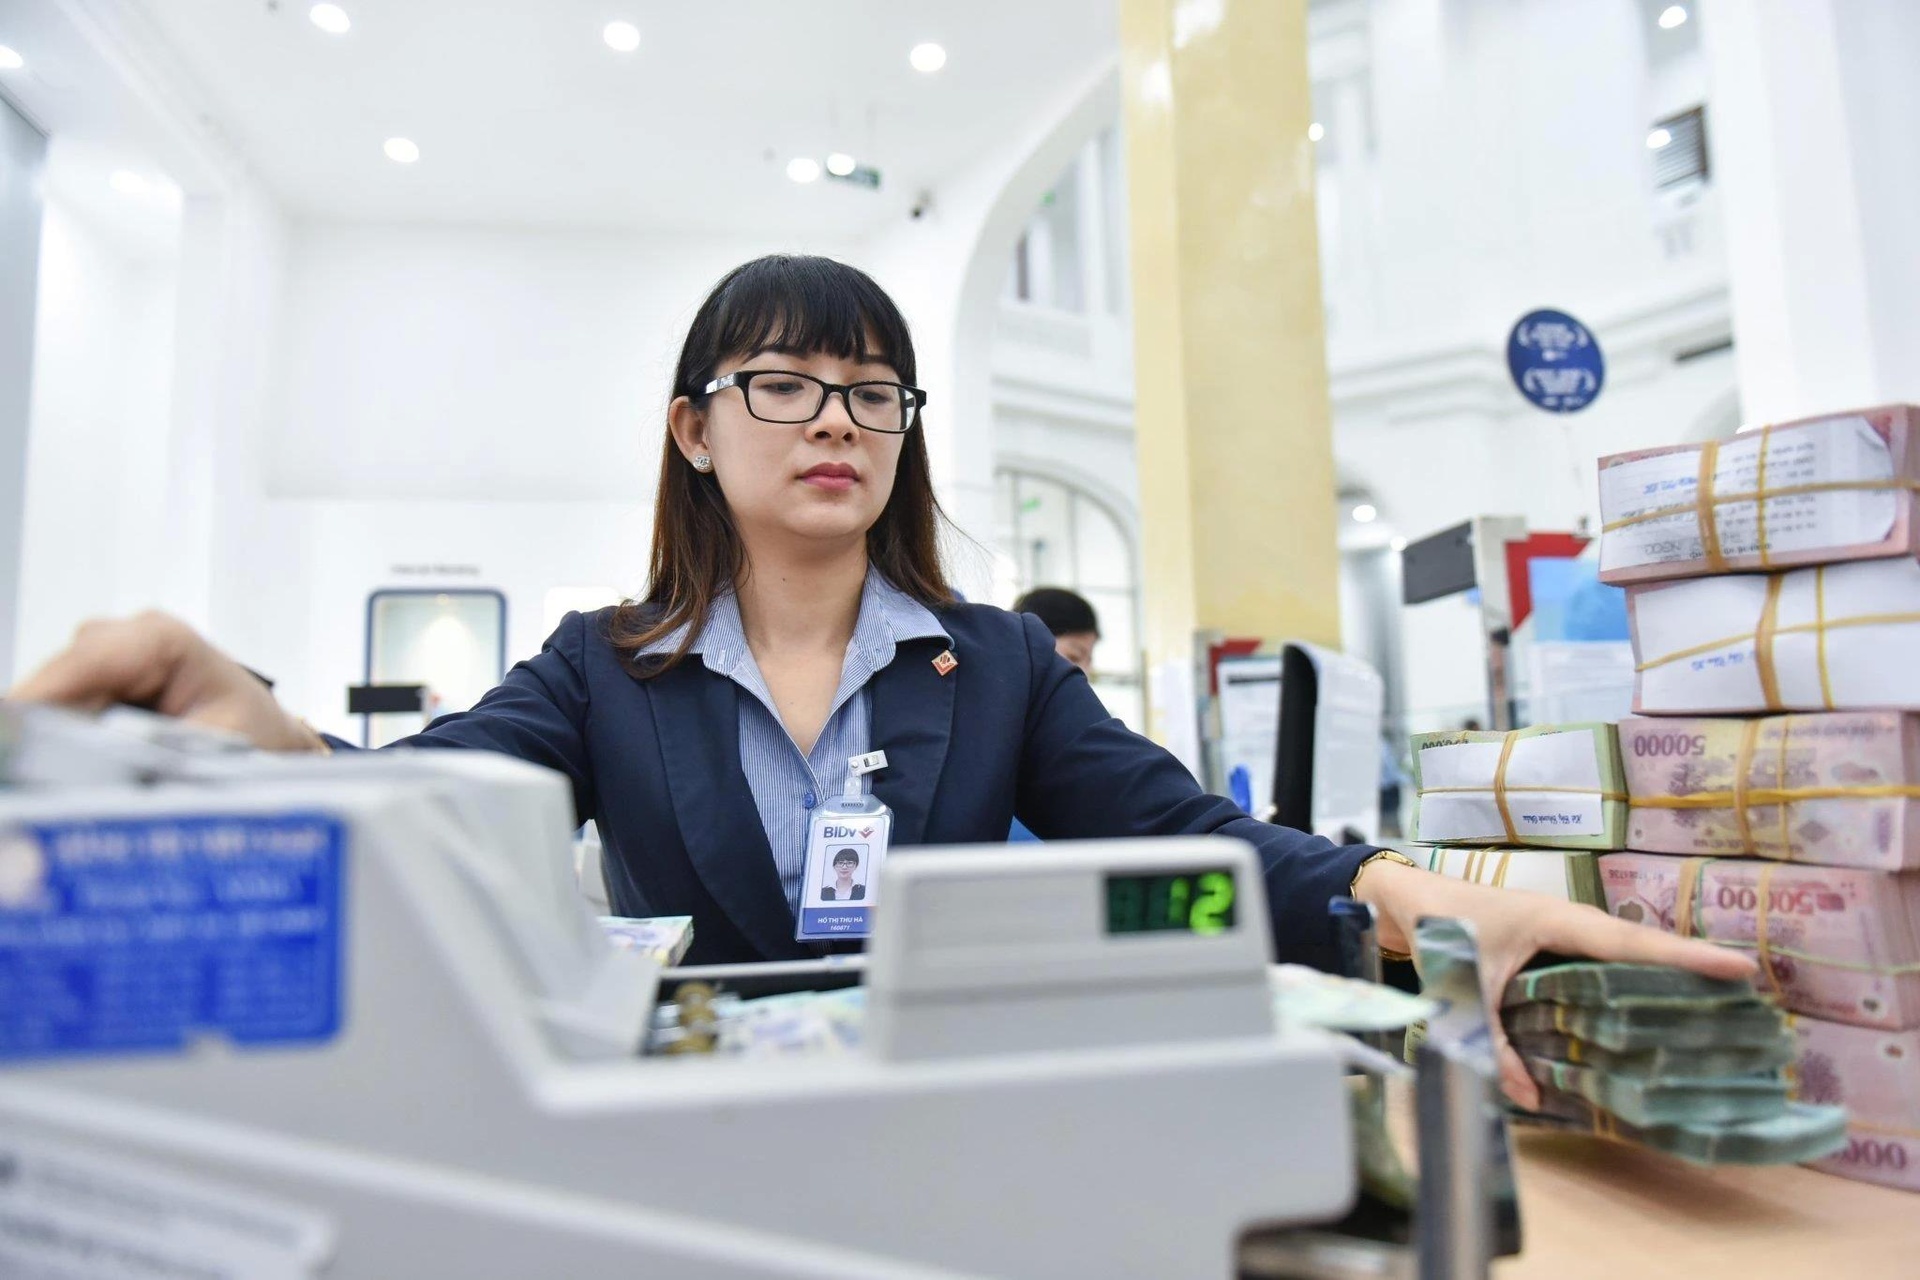
Banks need to strike a balance among lowering corporate borrowing costs, retaining deposits, and controlling lending risk. Source: https://znews.vn/
Can Rate Cuts Drive Businesses to Increase Investment?
Even if banks cut rates, businesses may not be able to borrow. SMEs often fail to pass reviews because of insufficient collateral, unstable cash flow, or incomplete financial data; even having orders may not be an exception.
For rate cuts to truly drive investment, banks could, when assessing companies, look more at order contracts, e-invoices, tax records, and accounts receivable, and combine this with order financing, supply-chain financing, and other methods.
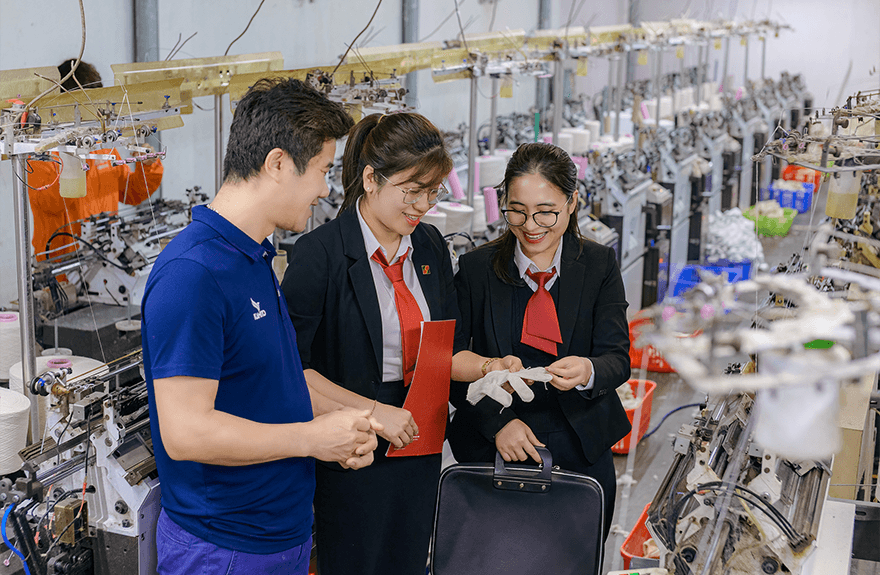
Rate cuts are only the first step. SMEs also need suitable credit methods to use funds for production and taking orders. Source: https://thitruongtaichinhtiente.vn/
The central bank’s demand that banks cut rates is intended to reduce funding costs, support growth, and at the same time safeguard banking risks. Next, it remains to be seen whether corporate borrowing rates fall, whether SMEs can obtain loans, and whether new funds bring investment and employment.
If rates are announced lower but businesses still cannot borrow or dare not invest, the policy effect will be limited. Only when funding costs, credit conditions, and market demand improve together can rate cuts possibly drive real growth.
Want to discuss investment opportunities or related topics in Vietnam? Please contact us:
Tel: +(886) 095 807 2379
Line: vnlandnote
WeChat: vnlandnote
For more updates and insights about Vietnam, please follow us:
Facebook: www.facebook.com/vnlandnote/
WeChat Official Account: hcmc101
-
 November 11, 2026
-
 November 5, 2026
-
 November 4, 2026
-
 October 29, 2026